
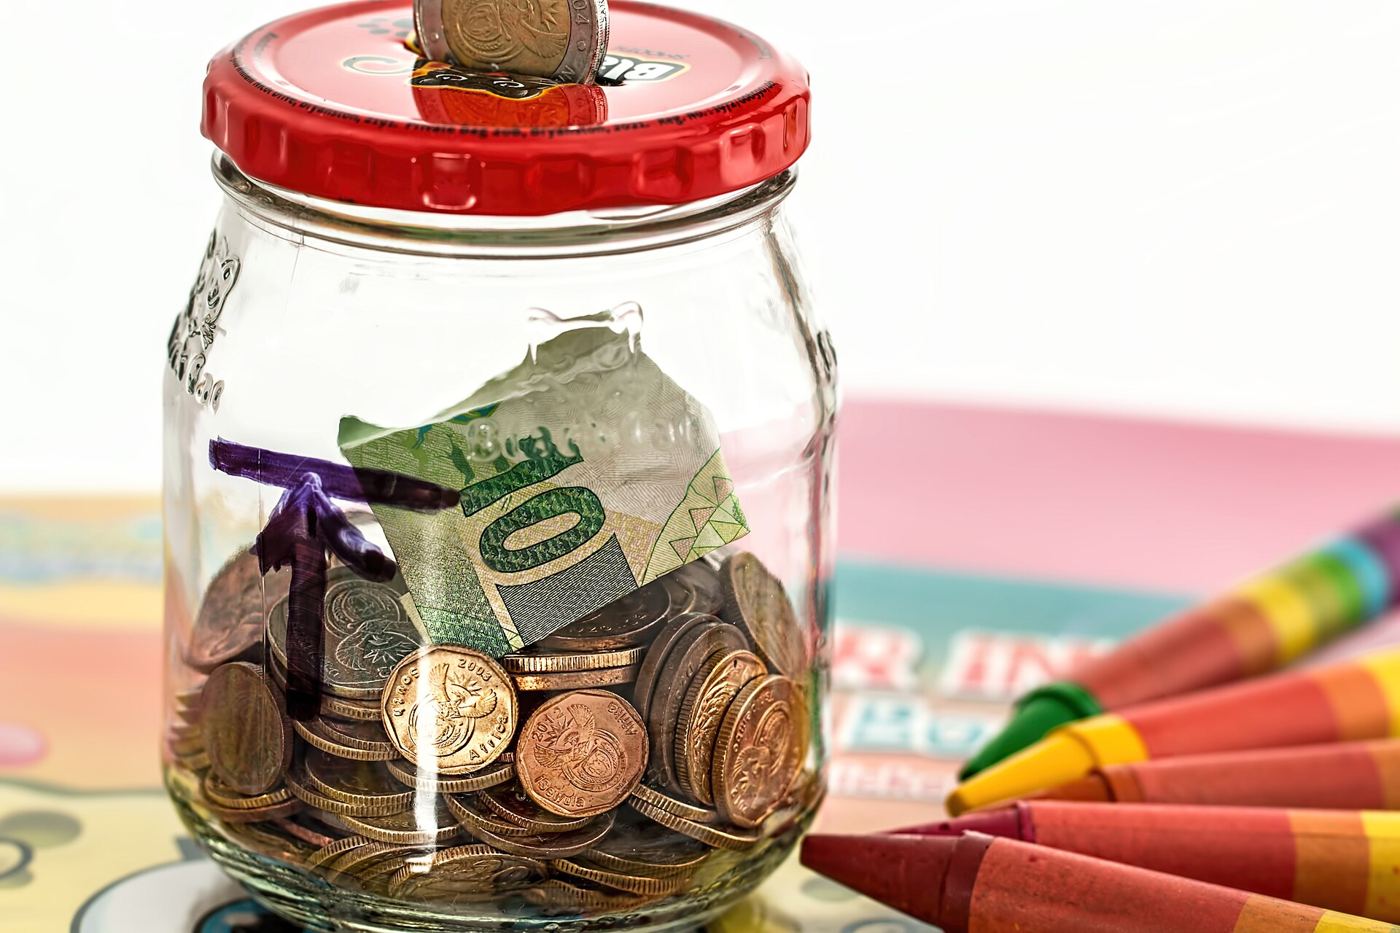
Some of the most effective saving habits are almost invisible. Rounding up everyday purchases to the nearest whole amount and moving the difference into savings is one example that has spread through banking apps in recent years. A coffee, a bus fare, or a weekly shop each contributes a few small coins, and on their own the amounts seem trivial. Over months, however, those fragments add up to a meaningful sum that the saver barely missed. The appeal lies in the lack of effort: once the feature is switched on, or the coin jar is placed by the door, the habit runs quietly in the background of daily life. Some savers enjoy watching the total climb week by week, and that visible progress provides motivation that a distant, abstract savings target often fails to deliver.
What the Evidence Shows
Behavioural researchers often note that people stick with systems that require little willpower, and round-up saving fits that description well. It works best alongside, not instead of, a regular savings plan, adding a gentle top-up rather than carrying the whole burden. Savers can also set simple rules, such as moving a fixed small amount every time they shop, or emptying loose change into the jar each evening. Periodically transferring the accumulated total into a proper savings account keeps the money organised and, in many cases, earning interest. The lesson is encouraging: building savings does not always require large sacrifices, only small actions repeated consistently over a long period. Reviewing the habit every few months keeps it healthy, ensuring the small transfers still fit the budget comfortably and that the growing pot is serving its intended purpose. Reporting and analysis from sources such as International Monetary Fund track the same developments, and specialists following round-up saving from spare change say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by round-up saving from spare change are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with round-up saving from spare change will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
There is a practical lesson in all of this for readers deciding what to do today. Start with the verified facts, be wary of anyone promising certainty, and prefer reversible steps while the evidence is still developing. Circumstances differ by country, income and personal situation, so general guidance should always be weighed against your own context before you act on it in any significant or lasting way.
